• About
  • How We Help
    How We Help
    Retirement and Tax Planning
    Investment Management
    Estate Planning Support
  • FAQ
  • Login
  • Resources
    Read the Blog

    Free financial education articles

    YouTube Videos

    Explainers, how-to's, and more

    Newsletter

    Sign up for our regular updates

    Events

    Join us for free education

  • Contact Us

Why Using QCD's Can Save Thousands In Taxes

October 9, 2026

People with charitable inclinations tend to give the same way. They give random amounts, in cash with no real tax strategy and no plan. 

But when they start to take RMD’s (required minimum distributions), this should change. 

Taking your RMD in cash to donate later could cost you tens of thousands of dollars in preventable taxes.

Here is the math:

If you have built a $3 million retirement portfolio—with $1.5M sitting in tax-deferred Traditional IRAs—your mandatory RMD at age 75 is approximately $61,000 per year.

Most high-net-worth retirees who give generously to charity follow a standard routine: they withdraw their RMD into their checking account, pay the taxes, and then write a check to their favorite charity.

That single habit creates a massive tax leak. 

Once RMDs kick in at age 73 or 75, those mandatory withdrawals get added directly to your taxable income—whether you need the cash flow or not. 

  • The Problem: A forced $100,000+ RMD doesn’t just generate income tax. It raises your Adjusted Gross Income (AGI), which can trigger IRMAA Medicare surcharges, subject more of your Social Security to taxation, and push you into a higher federal tax bracket. 
  • The Reality: Standard charitable deductions rarely help high-net-worth retirees who claim the standard deduction or face SALT caps. Writing a personal check from your bank account leaves valuable tax savings on the table. 

So what is the solution? There are several for those who are taking Required Minimum Distributions:

  • Take advantage of a Qualified Charitable Distribution- The IRS allows individuals age 70½+ to transfer up to $111,000 per year directly from an IRA to a qualified 501(c)(3) charity tax-free. For a married couple with separate IRAs, that is $222,000 annually removed from your future taxable estate while satisfying all or part of your RMD. 
  •  May protect you against IRMAA Surcharges & Net Investment Income Tax (NIIT) Because a QCD excludes income from your return altogether rather than acting as a deduction, it lowers your overall AGI. Keeping your AGI under key thresholds protects you from tier-based Medicare Part B and D premium penalties and the 3.8% NIIT on investment income. 

Take caution and mind the IRS "First-Dollar" Rule.  By law, the first money distributed from your IRA in a calendar year satisfies your RMD. If you take a personal cash distribution in January, you cannot retroactively classify a later charitable gift as your RMD. Schedule your QCDs at the start of the year before taking personal withdrawals. 

Let’s look at a retiree in the 32% federal tax bracket who wants to give $30,000 to charity out of their $61,000 RMD.
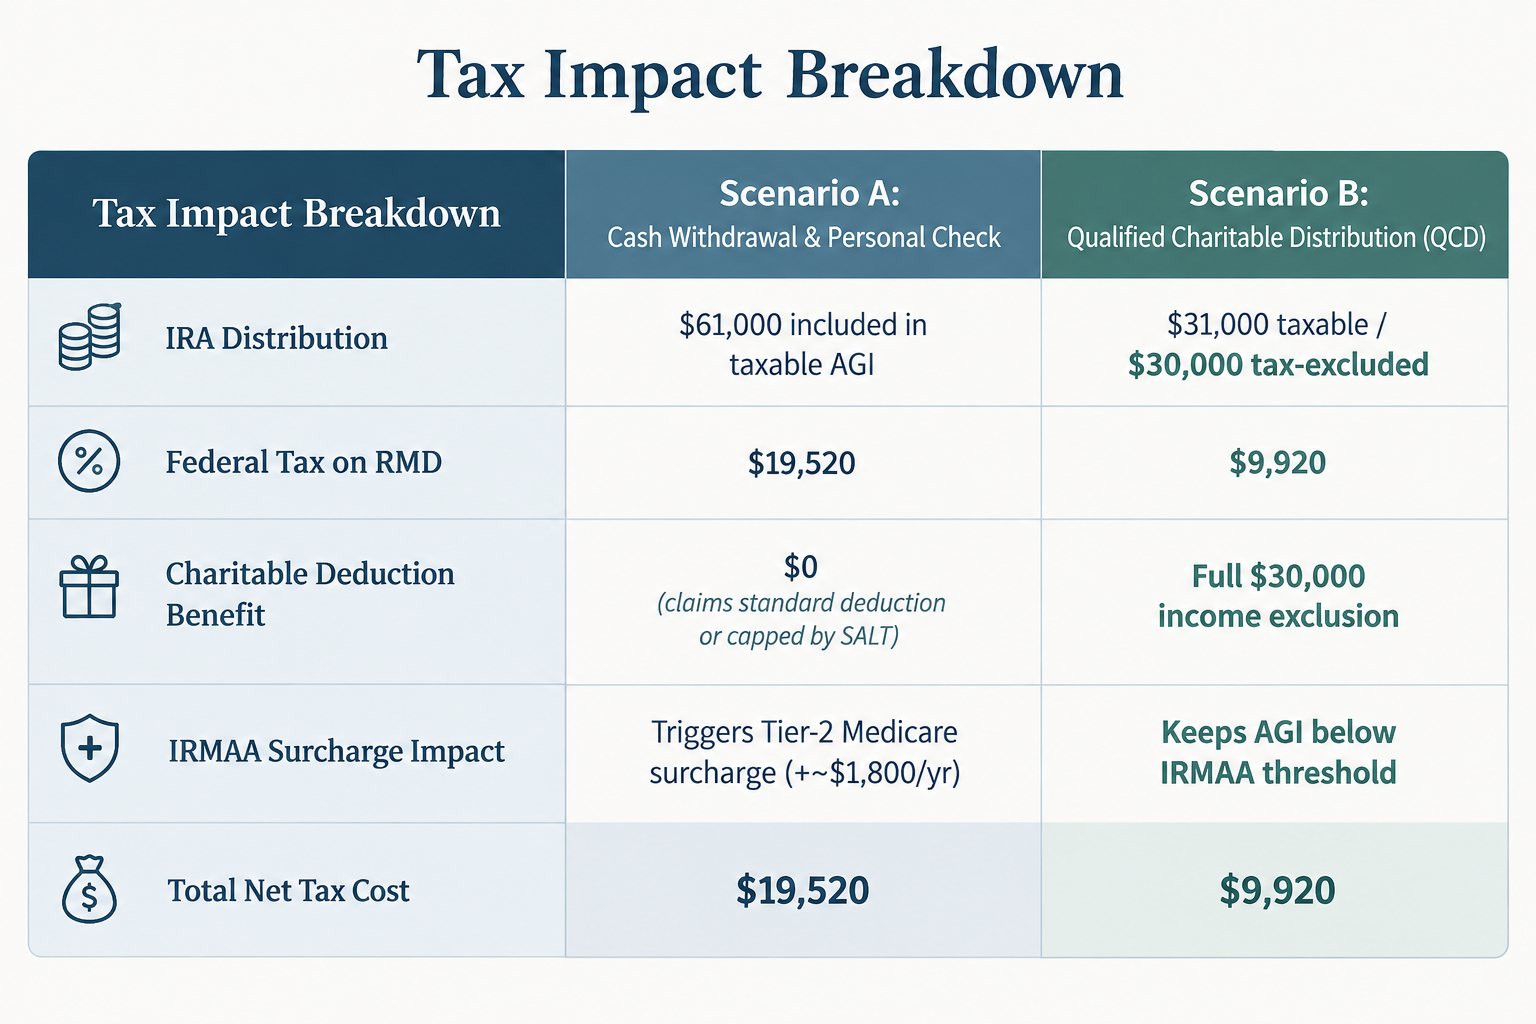
Why the difference is so stark: A standard deduction or itemized threshold often absorbs cash gifts without lowering your top-line Adjusted Gross Income (AGI). A QCD bypasses AGI entirely—saving this retiree nearly $10,000 in a single year. 

For a $3M portfolio, a Qualified Charitable Distribution isn't just fulfilling your philanthropic choice—it has the potential to save tens of thousands of taxes, IRMAA surcharges preserving your estate.
A detailed financial planning engagement intended for those preparing to retire and are concerned about turning their nest egg into a paycheck

Financial advisor for those who have saved $1,000,000 or more for retirement

Talk with Sally
Phone: (603) 277-9953
Email: info@sjboylewealthplanning.com
Address: 45 Lyme Road, Suite 204A
Hanover, NH 03755
Contact UsJoin Our Newsletter
Quick navigation
AboutHow We HelpBlogContact
lEGAL
Form ADV Part 2AForm ADV Part 2BPrivacy Policy
Download our free retirement guide - a clear, easy‑to‑follow breakdown of health care costs, income planning, and managing debt in retirement. This guide gives you the key steps to build a stable, confident retirement plan. Enter your name and email below for instant access:
The Financial Guide
Click to Read Now
Oops! Something went wrong while submitting the form.
© SJ Boyle Wealth Planning. All rights reserved.
Designed by Converting Attention